Analysis shows that using a Mac can reduce overall business costs compared to PCs
Read more
TechCentral
techcentral.co.za

Analysis shows that using a Mac can reduce overall business costs compared to PCs

Using a Mac computer could potentially save businesses around R12,500 per device over five years. When calculated for an organization managing 100 laptops, this equates to a potential saving of 1.25 million rand.

These calculations are based on a study conducted by Forrester Consulting on behalf of Apple titled 'The Total Economic Impact of Apple Mac at Work,' which was completed in June 2026. The study modeled a total cost of ownership (TCO) saving of $760 USD per Mac over five years compared to PC devices. The amounts in rand are illustrative and calculated using an exchange rate of R16.40 to the dollar. Actual savings will depend on each specific organization's technological environment, operating expenses, and device management practices.

For South African enterprises facing pressure on margins, cash flow, and IT budgets, the study's findings raise an important question: are we truly measuring the actual cost of business technology, or just the amount we pay for its acquisition?

What the figures reveal

The Forrester study highlights several factors contributing to the long-term financial value of Macs:

  • A TCO saving of $760 (approximately R12,500) per Mac over five years, according to the study's financial model.
  • A 55% reduction in IT support calls, with the average cost of resolving each call decreasing by 25%.
  • Potential employee time savings of 100 minutes monthly due to faster startup, updates, and reduced troubleshooting needs.
  • Retention of 30% residual value after four years of operation, compared to 10% for PC devices, based on the study's assumptions.

To build a representative corporate organization, the study used survey and interview data to model the financial results. While these results are not guaranteed for all businesses, they demonstrate why the purchase price alone is an incomplete indicator of technology value.

Where the savings come from

The purchase price of a laptop is only part of its total cost. Throughout its service life, businesses also incur costs for implementation, management, security, maintenance, and eventual replacement.

IT support is a particularly significant aspect. Fewer technical issues mean less time spent diagnosing and fixing problems, and fewer disruptions for employees. Automated deployment, centralized device management, and optimized software updates can further reduce the administrative burden on IT teams. For companies with limited technical resources, this efficiency can be substantial. Instead of spending valuable time solving routine device problems, IT teams can focus on supporting business operations and improving systems.

Employee productivity adds another dimension. Although the potential time saving of 100 minutes per month identified in the Forrester model cannot automatically be considered monetary savings, reducing interruptions can increase the operational efficiency of the entire staff.

Mac's built-in operating system and security features can also reduce the need for certain additional software licenses and management tools, depending on the organization's needs. These are less obvious costs that businesses must consider when comparing devices.

Long-term value with planned replacement

Another important element of the Mac's financial proposition is its durability. Robust hardware, Apple Silicon performance, and continuous software support help Macs remain productive and reliable for several years. In the Forrester model, the organization operated within a four-year lifecycle for Macs, unlike the previous three-year cycle for PCs.

However, a longer device lifespan does not mean businesses should indefinitely postpone upgrades. Structured update cycles remain necessary for managing the technology fleet, controlling costs, and ensuring employees have devices that meet their evolving requirements. The key is finding a balance between the useful life of a Mac and the financial and operational benefits of timely upgrades.

Residual value plays a crucial role in this decision. The Forrester model assumed that a Mac would retain approximately 30% of its initial cost after four years, compared to 10% for PCs. While the actual resale value varies, recovering a significant portion of the initial device cost can help offset subsequent investments. For enterprises managing large fleets, planned upgrades and structured buyback programs can make technology costs more predictable.

Making smarter technology decisions

Whether a business is considering switching from PC to Mac or planning its next Mac upgrade, one financial principle remains constant: the best investment is not necessarily the device with the lowest purchase price or the longest possible lifespan. It is the device that provides the greatest value throughout a properly managed lifecycle.

Digicape helps businesses assess the full picture, from selecting the right Mac for various workloads to financing, deployment, ongoing support, and upgrade planning. Understanding these costs allows companies to make more informed purchasing decisions, manage their technology budgets effectively, and maximize the value of their investments.

Make your next technology investment count

Whether you are considering switching to Mac or planning device upgrades, Digicape can help you evaluate long-term costs, explore financing and buyback options, and find the right solution for your business. Contact our business team to discuss your requirements.
Similar stories

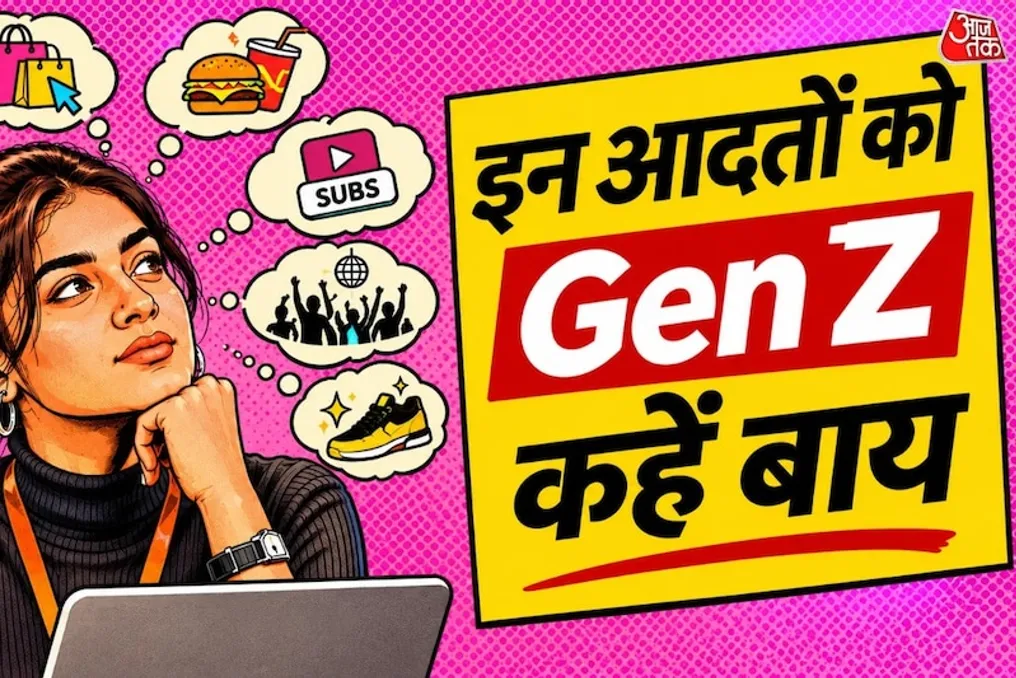
Five Expensive Habits Gen Z Should Quit to Keep Their Budget
Read more
www.aajtak.in

Five Expensive Habits Gen Z Should Quit to Keep Their Budget

Generation Z tends to believe in the possibility of earning money at a young age and living on their own dime. However, some small habits can derail the budget by the end of the month. Among these habits are online shopping and eating out; it is important to pay attention to them to understand five costly habits that Generation Z can give up to save money.

The first of these habits is making unnecessary online purchases. When seeing sales, discounts, and new collections, people often buy things they do not need. Constant purchasing of clothing, shoes, and accessories can prove very burdensome for the wallet.

The second problem is ordering food from outside every day. Thanks to online food delivery services, it has become easy to order food. Nevertheless, daily orders of coffee, snacks, and full meals lead to significant expenses over the course of a month. This expense can be reduced by eating at home.

The third habit is keeping subscriptions that are not used. Many people sign up for various subscriptions to watch movies, listen to music, and receive other services, but often they do not use them. In such cases, it is better to cancel these subscriptions.

The fourth habit is going to parties every weekend. Going out with friends, dining in expensive restaurants, and regular parties may seem pleasant, but this behavior can disrupt the monthly budget. To prevent this, it is necessary to set specific limits in advance.

The fifth habit is buying expensive things for show. Sometimes, observing the lifestyles of others on social media, people start buying expensive phones, branded clothing, and accessories. However, spending one's earned money solely to show off to others is not a wise decision.

In conclusion, it should be noted that managing money correctly is just as important as earning it. If Generation Z pays attention to these small habits, it will be able to save a lot without sacrificing its lifestyle.

What is soft saving: Generation Z is changing the approach to savings
Read more
www.aajtak.in

What is soft saving: Generation Z is changing the approach to savings

Saving money has always been considered a virtuous habit. Previously, people would set aside a significant portion of their income for future needs, such as buying housing, educating children, and retirement. However, among Generation Z, a new method of financial management called soft saving is gaining popularity.

With soft saving, young people aim not only to save money for the future but also to fully enjoy life in the present. Instead of saving all their earnings, they prefer to spend some money on entertainment, purchasing desired items, and personal expenses.

Soft saving implies the absence of rigid rules regarding accumulation. People set aside a certain amount for the future, but cover their current needs and desires with the remaining funds. For example, instead of saving a large sum monthly, a young person might save a small amount, using the remaining funds to attend concerts with friends or buy favorite goods.

Traditional saving focuses primarily on financial future. People concentrate on regularly setting aside a fixed amount, investing, and achieving long-term goals. In contrast, soft saving gives equal importance to living in the here and now and does not deem it necessary to forgo every small pleasure for the sake of savings. Nevertheless, this does not mean that young people stop saving altogether.

Generation Z faces serious economic challenges, such as inflation, rising rent, labor market instability, and difficulties in acquiring housing. Many young people feel that even with active saving, very big goals can be hard to achieve. Therefore, they want to spend part of their income on today's pleasures and experiences, as they believe it is wrong to constantly postpone life.

Social media has also contributed to the formation of this concept. By viewing content about travel, fashion, concerts, and lifestyle on Instagram, young people strive to gain new experiences. They believe it is important to spend money on things according to their taste, rather than just increasing their bank balance. For them, a happy life includes not only financial security but also creating pleasant memories.

Soft saving does not mean that Generation Z completely ignores the future. It is more of a desire to find a balance between savings and spending. They want to keep some income aside for emergencies and future needs, but at the same time, they do not want to put off every joy until later. Furthermore, excessive spending without any plan is not soft saving.

Soft saving demonstrates that for Generation Z, financial success is not solely about accumulating large sums. They want to have both savings for the future and funds to live life as they choose today. While traditional saving focuses on protecting the economic future, soft saving tries to find a balance between the present and the coming times. Thus, for Generation Z, it has become important not just to save money, but to use it correctly.

The trend of soft saving shows that Generation Z is changing its attitude towards money. For them, simply accumulating funds for the future is not enough; living in the present according to one's preferences is also very important. They do not want their small joys to be left behind due to concerns about savings. However, alongside this attitude, it is important to understand financial responsibility. Ignoring future needs for present spending is not the right decision. True wisdom lies in combining savings and enjoying life.

Popular