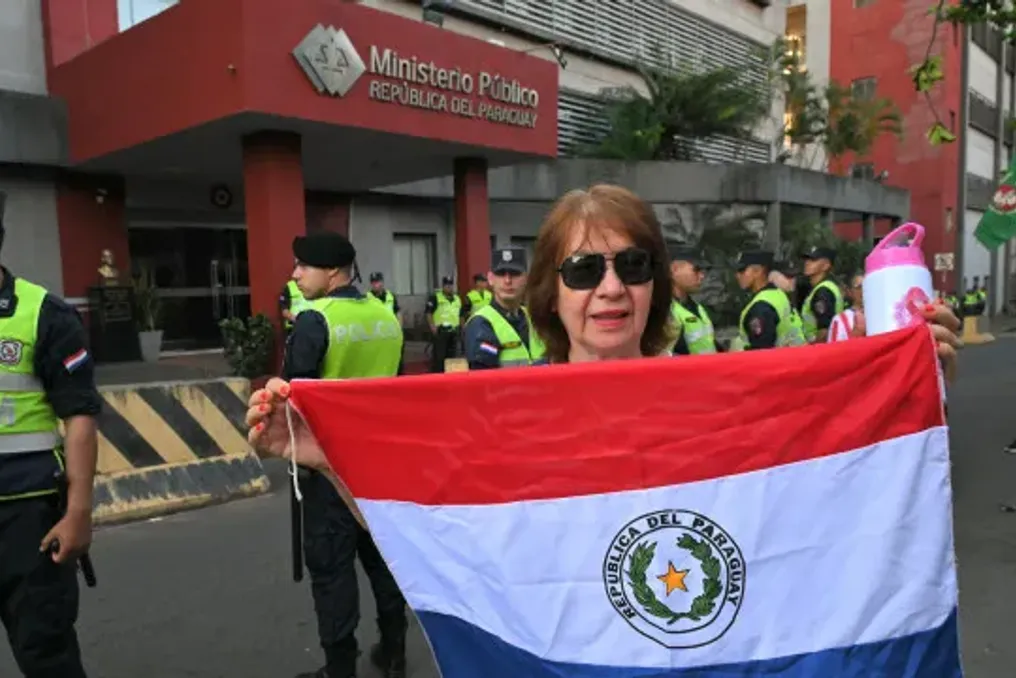
The Central Bank of Paraguay (BCP) liquidated the digital bank Ueno this week. It is estimated that 60% of the country's adult population held an account with this bank, which managed approximately US$ 850 million (equivalent to R$ 4.6 billion) in public funds.
The decision to liquidate Ueno was made after the BCP identified irregularities in loans granted to companies linked to the bank itself, finding, in summary, a capital insufficiency. The intervention by the Paraguayan Central Bank resulted in the blocking of accounts and investments, causing immediate difficulties for account holders.
In this crisis scenario, the President of Paraguay, Santiago Peña, resigned from office. It is relevant to note that Peña had been a shareholder in the Vázquez Group, which controlled Ueno bank, until March 2025. Furthermore, Peña appointed Carlos Carvallo, the former president of the bank, to lead the Paraguayan Central Bank in 2023.
Experts from Olhar Digital debated the liquidation of Ueno, financial security, and the impacts of crises such as the Paraguayan digital bank and Master bank. Ueno Bank was one of the largest digital banks in Paraguay, but its solvency ratio fell below half of the minimum legal requirement, forcing the cessation of activities.
The solvency ratio measures an institution's ability to honor its long-term commitments and absorb losses without failing, indicating whether assets exceed debts. In Ueno's case, the bank accumulated a significant financial deficit by concealing illicit loans and defaults from companies controlled by its own controller, losing solvency due to a lack of real reserves to cover withdrawals.
The collapse of Ueno bank froze the applications, cards, and funds of its approximately three million clients. An independent study by Equifax Paraguay SA revealed that Ueno allowed more than one million Paraguayans without banking history to enter the financial sector, and these people were left unsupported.
Lea Vidigal, a Doctor of Economic Law from USP and partner at Lea Vidigal Advocacia, commented that the sudden closure with service blocking leads many people to prefer physical cash. She observed that this retreat manifests in social behavior. For Vidigal, the Ueno case demonstrates that size does not guarantee solidity.
Pedro Saad Abud, a capital markets specialist, agreed, stating that what sustains an institution is capital, liquidity, governance, and a sustainable business model. When questioned about how to ensure the safety of money, Vidigal pointed out that there are layers of protection, and the client must know where they stand.
The first layer involves knowing who legally holds the money. Vidigal clarified that many fintechs are payment institutions, not banks. In banks linked to the Credit Guarantee Fund (FGC), checking accounts, savings, CDB, RDB, LCI, and LCA are covered up to R$ 250 thousand per CPF or CNPJ in each institution or conglomerate, with a global limit of R$ 1 million every four years. However, balances in payment accounts are not covered by the FGC, being protected by law as separate assets.
The second layer is the client's behavior: it is crucial to respect the FGC limits and diversify investments across different conglomerates. The lawyer advised that large reserves can be kept in government bonds and that the Central Bank's website should always be checked to verify if the institution is authorized and what its nature is, warning against returns much higher than the market, as the FGC is not a quality seal.
The third layer is independent supervision, something that does not depend on the client. Vidigal criticized the fact that the president of the Paraguayan central bank came from Ueno itself, classifying a compromised regulator as a risk that the client cannot mitigate alone. In contrast, Pedro Saad Abud mentioned that in Brazil, the regulatory environment has been strengthened, citing the post-Master case requirement for excessively leveraged banks to keep part of their resources in government bonds, in addition to the gradual recalibration of the minimum required capital until 2028.
Nathália Carmo, Information Security specialist and COO of IAM Brasil, highlighted three crucial aspects for money security: the financial health of the bank, the protection applied to the deposit, and the security of transactions. Carmo emphasized that an application may have good authentication mechanisms but belong to an institution with financial problems.
In the Brazilian context, the first precaution is to consult the Central Bank's registry to identify the actual institution holding the account or issuing the investment, which helps validate the operation, although authorization does not eliminate risks. Regarding cybersecurity, her recommendations include protecting the mobile phone, using additional authentication, activating alerts, and never sharing passwords or codes. She also suggested distributing resources among different conglomerates to reduce risk concentration.
For Carmo, the main consequence of the Ueno case in Paraguay is the erosion of trust. The difficulty in accessing one's own money can undermine belief in the digital environment for those entering the financial system. She emphasized that the Ueno and Master crises are not caused by cyberattacks, preventing the public from mistakenly associating innovation with risk.
Abud added that loss of confidence can alienate the most vulnerable public. Carmo added that financial crises open loopholes for fraud, as the urgency to recover funds makes the client more susceptible to scammers. For her, democratizing access requires more than just opening accounts; institutions must offer clear service, explain risks, protect data, and maintain rigorous controls, a responsibility that cannot be entirely transferred to the consumer.
Vidigal differentiated between banking and financial citizenship. She explained that having an account is just access, while financial citizenship, according to the Central Bank of Brazil, is the exercise of rights and duties to manage resources well. This citizenship is built through education, inclusion, and consumer protection. In summary, anyone who uses a cell phone without knowing if the money is guaranteed or whom to turn to in case of closure is included, but does not yet exercise full financial citizenship.
Both experts agreed that the bankruptcy did not occur because they were digital banks. Vidigal stated that Ueno lent above legal limits to companies linked to the owners, in an environment where the bank, regulator, and Presidency were very close. Master, on the other hand, grew by raising funds through CDBs above the market, relying on the FGC. The core of the problem, according to her, lies in old governance failures, conflicts of interest, and supervision, regardless of the technological guise.
Vidigal concluded that technology optimizes processes but does not replace prudential regulation. Inclusion without supervision generates exposed clients. The most important lesson is to separate the institution's infrastructure, citing Pix as an example of public infrastructure operated by the Central Bank. When an institution fails, the client loses the account, but not the payment method, which can be registered elsewhere. Digitalization resists crises when the infrastructure is public, the client knows what is protected, and there is effective supervision.