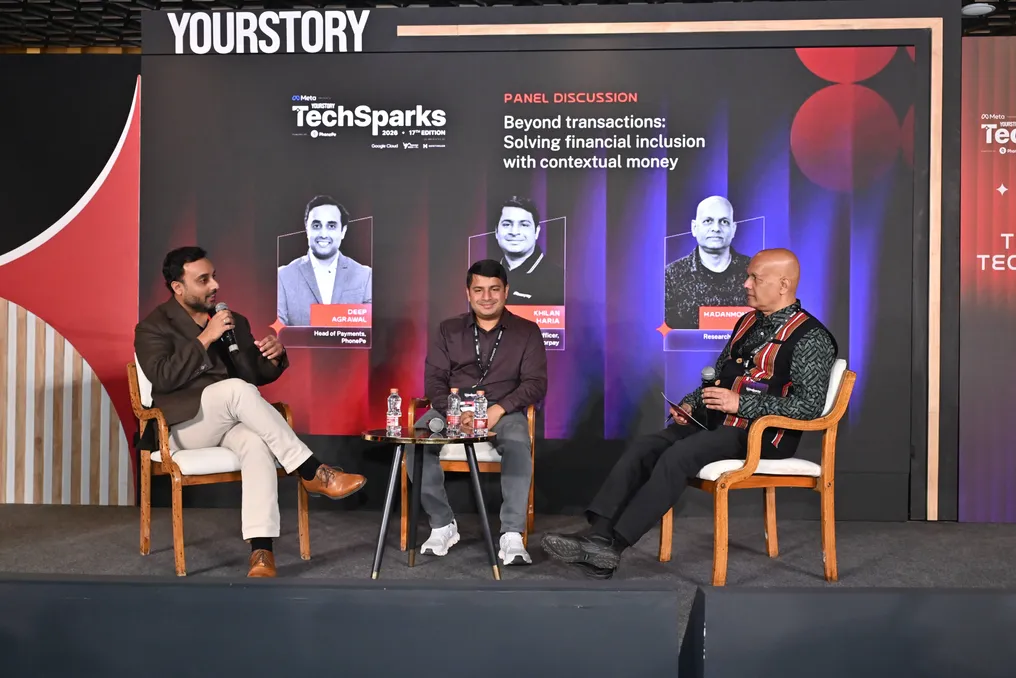
India has simplified digital payments to the level of scanning a QR code. The next stage of development involves using payment systems to connect consumers with suitable financial products and helping businesses overcome the challenges of growing online commerce.
At the TechSparks 2026 event, Dip Agarwal, Head of Payments at PhonePe, and Hilan Khariya, Product Director at Razorpay, participated in a panel discussion with Madanmohan Rao, Director of Research at YourStory. The discussion focused on the topic 'Beyond Transactions: Solving Financial Inclusion Challenges with Contextual Money.'
It was noted during the discussion that payments are becoming part of a broader digital experience, helping to increase transaction success rates and aiding in customer acquisition and retention for sellers.
Agarwal mentioned that digital payments have become an everyday reality for over 500 million UPI users, who use this system to send money to friends, pay electricity bills, make online purchases, and shop in stores.
However, the next task is to integrate another 500 million people into the digital payments ecosystem while providing existing users access to financial products beyond simple payments.
For businesses, accepting payments is just the beginning. Khariya reported that Razorpay's experience with millions of small and medium enterprises (SMEs) has shown that sellers face several difficulties after setting up payment collection infrastructure, including customer acquisition, conversion rate improvement, and stimulating repeat purchases.
He emphasized: 'Over these years, we have learned by working with millions of such SMEs. A bigger problem sometimes goes beyond payments. Payments are what I now call the core infrastructure that SMEs need to set up their digital commerce or online business. But besides that, what most businesses struggle with is the question: how do I get demand? How do I maximize retention? How do I increase conversion?'
Initially, Razorpay addressed some of these needs through payroll and vendor payment products. However, conversations with sellers revealed that businesses needed support beyond money management; they also required help in building and developing their online operations.
Khariya added that assisting more small businesses in establishing an online presence and succeeding in digital commerce can contribute to the growth of India's digital economy.
Every digital transaction generates data that payment platforms can use to better understand customer needs, identify risks, and improve the payment user experience.
Khariya introduced Razorpay's transaction-based model, Vulcan 5.2, which is designed to understand what he termed the 'language of payments.' According to him, each transaction contains nearly 3000 attributes. By analyzing them, the model can predict missing information, assess fraud probability, and determine the likelihood of a transaction converting.
This allows companies to detect suspicious activities, mitigate risks, and increase the chances of turning potential buyers into paying customers. Khariya explained that traditional machine learning usually involves pattern detection, hypothesis development, and training models around them. However, transformer-based models are capable of detecting finer patterns that might be elusive using traditional methods.
At PhonePe, machine learning is applied to enhance payment reliability. Agarwal discussed an internal model called Kill Switch, which predicts the probability of a transaction completing successfully. This model considers factors such as bank response time and recent transaction success rates to estimate the probability of a successful payment.
Agarwal noted: 'Consumers don't actually care if a transaction fails. What worries them is that it remains in a pending state.' He continued: 'In this model, we inform the customer even before they initiate the transaction that their bank might not be working and advise them to try the transaction again later.'
This approach helps build trust and encourages users to return to the platform. Transaction context can also help payment platforms recommend financial products based on customer needs. For example, a customer booking an international flight through PhonePe might receive a recommendation for travel insurance. For someone traveling only within India, bus booking might be more relevant.
Agarwal explained that PhonePe uses guardrails in its algorithms to avoid recommending products irrelevant to individual customers.
Razorpay also uses AI to assist sellers in managing daily business operations. Khariya described two initiatives—Ray and Agent Studio—created to improve the accessibility of business support and automation. Ray is an AI assistant functioning as a customer relationship manager for businesses. While large clients usually have dedicated managers, scaling such support for small sellers was a complex task.
Ray aims to bridge this gap, allowing sellers to describe their issues via voice notes or WhatsApp messages in simple English, without needing to navigate complex dashboards and consoles.
Agent Studio goes further, enabling businesses to use autonomous AI agents to perform specific tasks. These tasks include recovering abandoned shopping carts, representing seller interests in disputes, confirming Cash on Delivery orders, and verifying delivery addresses.
Khariya reported that Razorpay has launched 12 agents used by 600 brands, some of which use multiple agents. The company plans to increase the number of agents to 100 within the next six months and ultimately reach 100,000 businesses using them.
Agarwal also discussed how AI-based tools can help bring more people into the digital payments ecosystem. He highlighted the difficulties faced by feature phone users, many of whom live in small towns and rural areas or are just starting to participate in the formal economy. Feature phones have several limitations, including the inability to receive over-the-air software updates. Users may also require assistance with processes familiar to more digitally savvy consumers.
To address these issues, PhonePe has implemented voice bots that help users perform tasks such as linking bank accounts and setting up UPI PINs. PhonePe is also working to facilitate micro and small sellers in starting online sales. Creating a website using platforms like Shopify or WooCommerce can be expensive and complicated for young entrepreneurs. PhonePe's SmartPages product aims to simplify this process, allowing sellers to create a checkout page, list products, and start selling without hiring a web developer or subscribing to a more complex platform.
India's digital payment ecosystem has simplified daily transactions for millions of people. In the view of Agarwal and Khariya, the next opportunity lies in leveraging this infrastructure to solve a wider range of consumer and business needs. From enhancing payment reliability and providing relevant financial products to assisting sellers in operations management and customer acquisition—contextual payments and AI can expand the role of payment platforms beyond simple transactions.