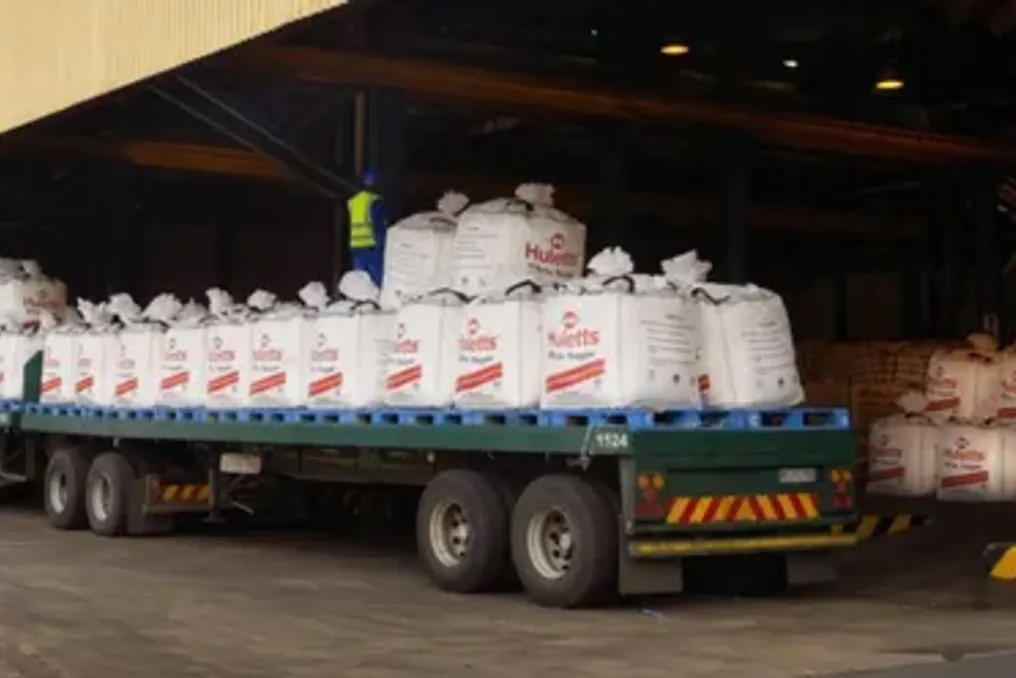
Tongaat Hulett faces wage crisis ahead of JSE delisting in November
Read more
IOL
iol.co.za

Tongaat Hulett faces wage crisis ahead of JSE delisting in November

Sugar giant Tongaat Hulett is facing the threat of a financial crisis, putting approximately 250,000 jobs at risk. The situation was the subject of a private meeting initiated by KwaZulu-Natal Police Commissioner, Lieutenant General Nlanhla Mkhwanazi. The meeting included Tongaat Hulett management, the Industrial Development Corporation, representatives of the Zulu Royal Court, and sugarcane producers to discuss the salary payment issue and the company's upcoming delisting from the JSE on November 3rd.

According to SAPS KZN representative, Colonel Robert Netsiundu, the meeting was prompted by concerns that the October wages might be the last paid to employees, threatening the loss of 250,000 jobs. Although Tongaat Hulett directly employs about 3,000 people in South Africa, its supply chain is extensive. The South African sugar industry supports roughly 65,000 small farmers and 270,000 indirect jobs, most of which are concentrated in KwaZulu-Natal.

The collapse occurs when processing plants stop operating, preventing producers from delivering cane, and transporters cease operations, leading to the decline of rural settlements. The figure of 250,000 cited by the police reflects this entire ecosystem. The immediate trigger was a lack of funding. Since 2023, Tongaat Hulett has been operating on financing from the IDC, amounting to 2.75 billion rand, but this package was due to expire on September 30th, and since then, the company has been operating on indefinite extension.

Without this funding, business rescue specialists cannot make payroll payments or pay for cane delivered by farmers. Tongaat Hulett will be delisted from the JSE on November 3rd, concluding a 74-year listing period that began in 1952 under the name J.L. Hulett & Sons. In 1982, it merged with Tongaat Group, becoming a South African sugar giant that, at its peak, owned over 500,000 hectares of sugarcane in South Africa.

The company's decline was accelerated by an accounting fraud scandal in 2019 involving seven executives, followed by the Covid-19 pandemic, floods in KZN in 2022 that damaged crops, and growing debt. At its peak, Tongaat Hulett owed banks more than 6.6 billion rand. After entering business rescue in October 2022, its shares were suspended and have not traded since.

The IDC intervened as the lender of last resort to prevent liquidation after the government opposed liquidation in February 2026, warning of serious consequences for workers and farmers. In June, IDC, Vision Group, and specialists signed a binding rescue agreement that halted immediate liquidation.

According to the Vision plan presented to King Misuzulu kaZwelitini on August 30th in Durban, the company plans to diversify beyond sugar production. Robert Gumede informed the King that Tongaat Hulett will produce ethanol for blending with gasoline, generate electricity from bagasse for Eskom and eThekwini, and convert carbon dioxide into medical oxygen. He noted that the company spends 7 billion rand annually, 40% of which goes to the King's subjects, and promised to increase the farmer base from 17,500 to over 30,000 and double the number of jobs.

This plan relies on the South African Sugar Agriculture Plan signed in April, which provides for a 4.5% ethanol blend in gasoline using a surplus of 300,000 tons of sugar. A similar model is applied in Brazil and India, where processing plants are energy producers. However, the Royal Court expressed concern. A letter from the King's private office to the Minister of Trade, Parks Tau, questioned the implementation of promises and demanded transparency regarding the IDC's 25% deal, as well as promised shares for workers and the community, approved by the Competition Commission.
Similar stories

Financial problems negatively affect the health, work, and personal lives of South Africans
Read more
iol.co.za

Financial problems negatively affect the health, work, and personal lives of South Africans

Financial pressure affects not only the ability to cover bills; for many residents of South Africa, worry about debt, job stability, investments, and pensions also worsens their mental state and complicates solving financial difficulties.

Kim Potgiter, Managing Director of Chartered Wealth Solutions, notes that uncertainty regarding money can quickly prompt people to envision the worst-case scenarios, constantly replaying the same fears without approaching a solution. According to her, without receiving new information or taking action, the situation does not change, and anxiety persists.

The scale of financial stress is reflected in the DebtBusters Money-Stress Tracker report for 2026, which surveyed nearly 18,000 subscribers who had not received debt counseling. The results showed that 72% of respondents experienced financial stress, an increase compared to the previous year. Among those affected, 75% reported that it affects their health, 76%—their work life, and 92%—their family life.

The pressure related to debt repayment has also intensified. More than half of those surveyed, specifically 53%, now spend more than 40% of their net income on debt payments, compared to 48% last year. Particular tension is observed among individuals aged 35–44, where three out of four spend more than 30% of their after-tax income on debt—a level described as unsustainable.

When worry becomes difficult to manage

Psychologist Dr. Andrea Kellerman, who analyzed the psychological consequences of the DebtBusters findings, states that prolonged financial pressure can weaken people's ability to make decisions and find ways to improve their situation. She notes that accumulated stress over the past five years has depleted the capacity to make more balanced decisions and think outside the box.

The proportion of DebtBusters respondents who felt stuck increased from 29% to 34%. Kellerman believes that constant stress can cause people to feel hopeless and helpless, potentially leading them to withdraw or avoid solving their problems. This can manifest as postponing decisions, unopened statements, delaying difficult conversations, or refusing opportunities that could help them.

Financial strain does not always mean a person misses payments or falls into arrears. Brett Kaminski, Director of Atlas Finance, says that people can make all payments on time while still spending a lot of time worrying about the next bill or how unexpected expenses will affect the household budget. He adds that financial stress can accumulate unnoticed, and even a small financial setback can seem overwhelming when there is virtually no financial cushion.

Where does the worry come from

Potgiter explains that people's attitudes toward money are often shaped by experiences and beliefs formed long before they started managing their own finances. In childhood, people absorb messages about whether money is abundance or scarcity, whether it causes tension, whether it is discussed openly or avoided, and how family members and those around them save, spend, and feel about it.

When these experiences are rooted in fear, scarcity, or guilt, they can influence financial decisions and a person's sense of security and well-being. Potgiter emphasizes that understanding the sources of this financial anxiety helps separate what is real in the current financial situation from what a person might be carrying from the past. She sees this particularly among people approaching retirement, who may worry for years about having enough funds without defining their actual financial standing.

In some cases, the numbers indicate the need for changes, while in others, people discover they are in a stronger financial position than they assumed. Potgiter concludes that 'knowing is better than guessing.' Although a financial plan cannot completely eliminate uncertainty, it can replace some assumptions and worst-case scenarios with facts, providing people with a concrete basis for action.

Regaining control

Kaminski argues that fighting financial stress does not mean immediately solving all problems. An important first step is early recognition of warning signs. He advises starting with a simple analysis of how much money comes in, how much goes out, and what payments are due before the next paycheck. Furthermore, budgeting can ease the mental burden of constantly calculating what is affordable. Reminders about debits, repayments, and other financial deadlines can reduce administrative pressure on people.

He also recommends that consumers who are finding it increasingly difficult to manage their budget seek advice from a creditor or request appropriate financial consultation before they fall into arrears. Potgiter also advises taking small, practical steps when financial problems seem insurmountable. Such steps may include opening a long-ignored statement, analyzing expenses, increasing investment contributions, or asking for help.

Popular