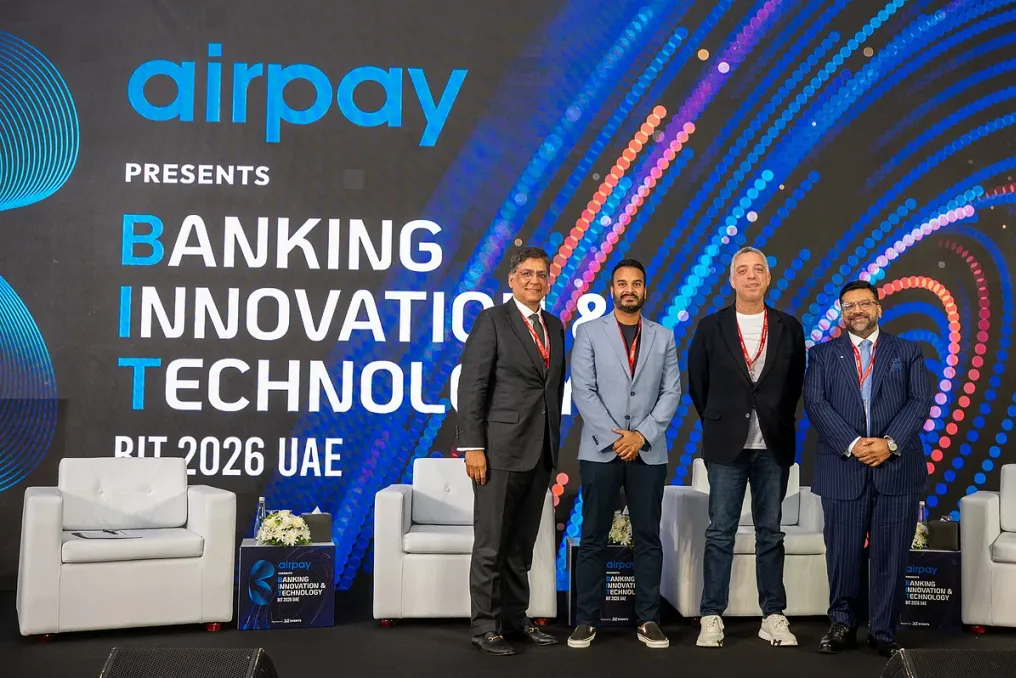
Industry leaders stated that lending in the United Arab Emirates (UAE) is gradually moving away from traditional credit scores. Fintech companies and banks are beginning to use alternative data to assess clients who may not have a formal credit history. This was mentioned at the Banking Innovation and Technology Summit (BIT Summit) in Dubai on Tuesday.
This shift allows lenders to make faster and more forward-looking decisions by analyzing data from payment systems, money transfers, and payroll to understand a client's financial behavior, as well as their willingness and ability to repay debt. For a significant portion of consumers, especially those without an established credit history, such data can open access to financial services that would otherwise be unavailable.
However, as financial institutions gain access to increasingly detailed customer data, the industry faces a related challenge: how deep should personalization be. Speakers at a separate discussion emphasized that transparency and explicit consent will become critical conditions for data-driven services to remain useful rather than intrusive.
Omayr Ansari, CEO and co-founder of ABHI, noted that lending has become a key focus area for fintech companies due to the margin it offers, and alternative data opens up new opportunities for client underwriting. He stated: 'Every fintech company dreams of becoming a bank, and all roads lead to lending when it comes to fintech because that's where the margin is, since you kind of establish that there is no more margin. Now the focus is on how you can underwrite to provide that lending.'
Ansari added that ABHI utilizes money transfer data across various markets, including the UAE, to support lending decisions, and also uses Wage Protection System (WPS) data in the UAE. He explained: 'These are alternative data that you can now use to provide credit services. We work with many money transfer providers (to access the data) who help us in underwriting decisions.' He also noted that 'most, 99.9% of our clients, for example, do not have a credit score, so you can extract data to underwrite and provide them with a basic level of service, which is our core product?'
Walid Hassouna, founder and group CEO of Valu, pointed out that the limitation of traditional credit scoring was its strong dependence on past borrower behavior. Analyzing the company's experience in Egypt in 2017, he reported that information from credit bureaus helped lenders make decisions based on clients' past actions. 'We used credit scoring. Credit bureaus essentially provided loans to clients who had previously taken out loans through official channels. So, we weren't really adding anything; we were just looking back at this information and making a decision.'
Hassouna continued that using multiple layers of data allowed lenders to make more prospective decisions. He stressed that changes in data improve risk assessment and customer acquisition. 'So, what we did (now) is use multiple market layers of data, and the good news is that every time a small change is made, our probability of default decreases, and the number of capital-attracting clients increases. And now we look forward, not backward.'
Amit Malhotra, Global Head of Retail Banking at Abu Dhabi Islamic Bank (ADIB), suggested that the future of lending will increasingly be defined by real-time finance and predictive modeling embedded in customers' daily lives. 'I think the future of lending and financing, as we know it today, can be described in a few words: real-time, predictive, absolutely data-driven, customer-centric or hyper-personalized, as we call it, and most importantly, timely.'
Malhotra also observed that instead of clients approaching banks only when they need financing, financial products are increasingly integrated into the overall customer journey. 'Today, consumption of finance actually happens based on how consumers consume the end product. Thus, more and more finance is being embedded into the ecosystem and the customer lifecycle.'
Nevertheless, the growing use of customer data raises another question: where should financial institutions draw the line? Basel Nezam, Vice President and Head of Value-Added Products at Network International, noted that obtaining customer consent itself can be complex, especially when companies try to make services more personalized. 'Sometimes saying it is easier than doing it, because interacting with the customer to get that consent can be difficult in itself. How do you provide personalization in a way that it doesn't feel intrusive? I think there are certain red lines that cannot be crossed.'
He warned that sensitive information, including medical transactions, could raise ethical concerns when used for personalization. 'For example, accessing people's medical transactions to give them advice... or for other (confidential) purposes raises ethical questions. There are certain boundaries that cannot be crossed. Consent is where you start.'
Dipak Sarup, Group Executive Vice President and Chief Corporate Development Officer at Thriwe, stated that transparency must accompany consent if banks and brands want to earn long-term customer trust. 'From an ethical and moral standpoint, I believe that customer consent is key. As far as brands and banks can go, they must be very transparent about how they obtain data and to what extent they intend to use it.'
Sarup added that explicit consent at every stage can turn data usage into part of a broader relationship of trust, rather than just a compliance requirement. 'If it is made maximally explicit to the end consumer, and there is explicit consent at every stage, I believe it is no longer just ticking a box. It is actually playing the role of a trusted partner.'
He cautioned that personalization that is not transparent to customers can quickly become unpleasant. 'Anything done in a somewhat hidden manner, without explicit manifestation to the customer, I suppose, borders on what becomes a little creepy.'