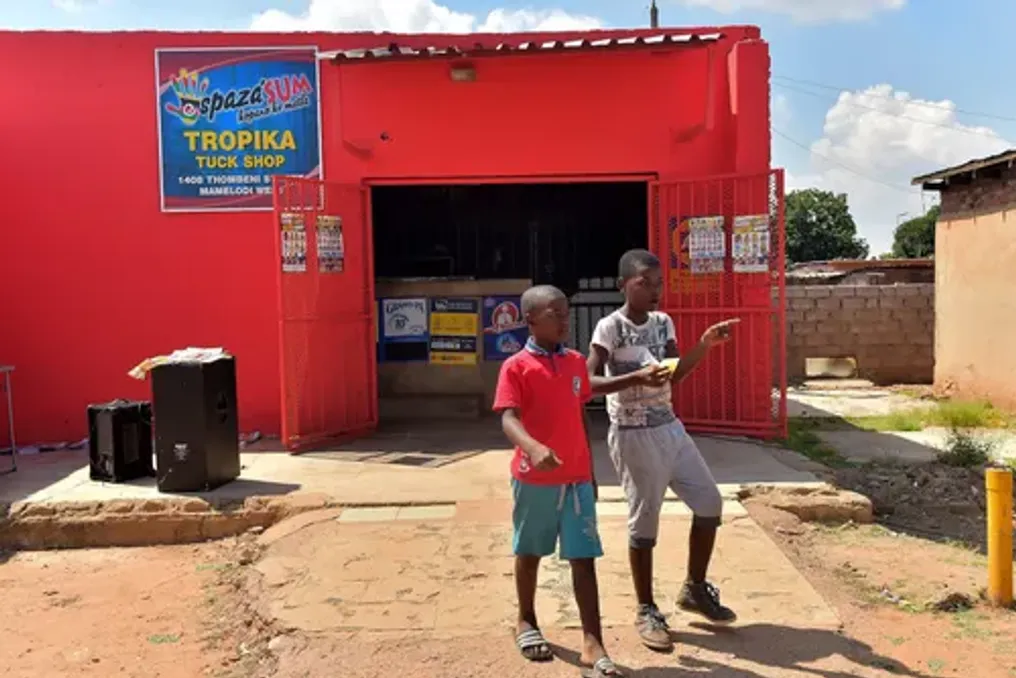
According to the report titled 'The Nature of Hidden Money Transfers in South Africa' (SADC Immigrant Insights Working in Tshwane's Informal Economy), informal businesses are being used to conceal financial flows. It was found that approximately 6.3 billion rand obtained by these shops was illegally moved out of the country.
These funds are transferred through unregistered SIM cards and unofficial money networks. Such uncontrolled financial flows have contributed to South Africa entering a grey zone due to weak anti-money laundering and counter-terrorism financing systems.
It is reported that these funds reached terrorist cells, including affiliates of the Islamic State (IS) operating in Kenya, Somalia, Nigeria, and Mozambique.
Of approximately 87,000 newly registered shops across the country, official government data indicates that about 32,824 (approximately 38%) are owned by non-South African citizens. However, regional estimates and informal sector data suggest that foreigners manage a much higher proportion (from 50% to over 70%) of unregistered or general informal shops in urban areas.
The report emphasized that the use of such channels often occurs outside formal financial systems, which can lead to money transfers that are neither recorded nor taxed in the migrants' country of residence nor in their country of origin.
'Consequently, tax authorities and financial regulators face significant difficulties in tracking financial flows, assessing their economic impact, and ensuring compliance with relevant fiscal and financial regulations,' the report states.
The study also warned that the growth of informal social networks, digital communication platforms, and community-level money transfer systems has created alternative financial ecosystems operating parallel to formal banking institutions. These networks facilitate the movement of funds while reducing transaction visibility for regulators such as the South African Revenue Service (SARS), the South African Reserve Bank (SARB), and other financial supervisory bodies.
Parliamentary committees, particularly the Portfolio Committee on Finance, have previously expressed serious concern over billions of rand leaving the country through uncontrolled channels, including cash generated by informal traders such as spaza shop owners. Members of parliament have consistently argued that these untaxed, illegal outflows deplete the national treasury and deprive public services of vital income.
SARS is actively targeting the spaza shop sector, valued at 200 billion rand, as part of an aggressive strategy to broaden the country's tax base. Although public and political pressure is increasing to strictly control establishments owned by foreigners, SARS does not differentiate in law enforcement based on nationality. Instead, it faces systemic structural obstacles across the entire informal economy.
Government data shows that only about 30% of spaza shops are registered taxpayers, meaning 70% are entirely outside the formal system. Most of these shops operate exclusively in cash or through informal, fragmented supply chains. The lack of point-of-sale reporting and official invoicing leaves SARS investigators with virtually no digital or paper trail to track.
Financial investigation consultant Emerald van Zyl noted that banks also supported terrorist groups. He stated that this action had a profound impact after the release of most political leaders from Robben Island in 1990. He added: 'Many people took up positions as cabinet ministers or bank directors, creating a conflict of interest that prevented them from holding banks accountable and ultimately led to the failure of consumer protection in South Africa.'
The SARB's 2025 report (Assessment of Risks of Money Laundering, Terrorist Financing and Proliferation Financing in the South African Banking Sector) showed that the South African banking sector faces high domestic risks of money laundering, terrorist financing, and proliferation financing, especially among larger domestic institutions. These crimes generate the largest, most frequent, and most integrated criminal proceeds into the banking system in South Africa, as confirmed by suspicious transaction reports, patterns of suspicious activity, intelligence surveillance, and case outcomes.
SARB, through its Prudential Authority (PA), announced a fine of 28 million rand for Capitec Bank last week. The fine was issued for administrative non-compliance with the Financial Intelligence Centre Act (FICA) following regulatory reviews conducted in 2023. The bank was fined as follows: 10 million rand for failures in comprehensive customer due diligence; 5 million rand for weaknesses in enhanced due diligence; 5 million rand for inadequate ongoing due diligence; 5 million rand for deficiencies in risk management policies (including terrorist ownership and financial sanctions reporting); and 3 million rand for non-compliance with staff training.
This followed an even larger administrative sanction decision of 56.25 million rand in December 2024 (of which 35 million was suspended). This penalty related to FICA violations discovered during reviews of retail and corporate banking between 2021 and 2022, which revealed identical issues, including delays in cash threshold reporting, lack of source of funds documentation, and poor risk management programs.
These fines are part of the regulators' aggressive enforcement strategy to clean up South Africa's financial systems after the country was placed in the grey zone by the global financial watchdog. Ultimately, South Africa exited the grey zone in October 2025.
According to the SARB report, the banking sector served approximately 80.2 million clients by the end of 2024. However, illegally present foreigners reportedly use informal financial mechanisms and, in some cases, access transactional services through proxy schemes or unverified funds.
SARB's analysis of financial transaction trends shows that local bank accounts primarily receive illicit income through money transfers, SWIFT transfers, EFTs, and cash deposits. The report indicated that a local bank, which disclosed information via SENS (Sasfin Bank), received administrative sanctions during the reporting period. These fines were issued for non-compliance with FICA, specifically in its foreign exchange division. Following these compliance breaches, SARS initiated legal action against Sasfin, filing a civil claim for damages totaling approximately 4.87 billion rand.
This lawsuit is based on an SARS investigation that revealed former foreign exchange clients formed a syndicate. They allegedly conspired with corrupt bank employees to illegally move funds abroad, deliberately concealing the audit trail to evade taxes.
The Financial Intelligence Centre (FIC) report for 2022 also highlighted the high risk of terrorist financing in South Africa, as up to 70% of cross-border money transfers in the region pass through informal, cash-based channels outside the formal banking system. The country is home to large diasporas from countries closely linked to terrorism, including Somalia, Kenya, Nigeria, and Mozambique. The report notes: 'Financial operations in these communities predominantly rely on cash. Unregulated alternative money transfer networks, such as Hawala and mobile money, are popular among low-income groups.'
'Cash transferred in this manner can be delivered directly to a specific conflict country or, more likely, to neighboring countries from where it can be transported overland across further borders. Cash moved across borders and outside the formal banking sector is difficult to detect and confiscate. A significant challenge is distinguishing between alternative money transfer systems used to send funds to the extensive diaspora in South Africa, as these systems are unregistered, unregulated, and operate outside the formal banking sector.'
_