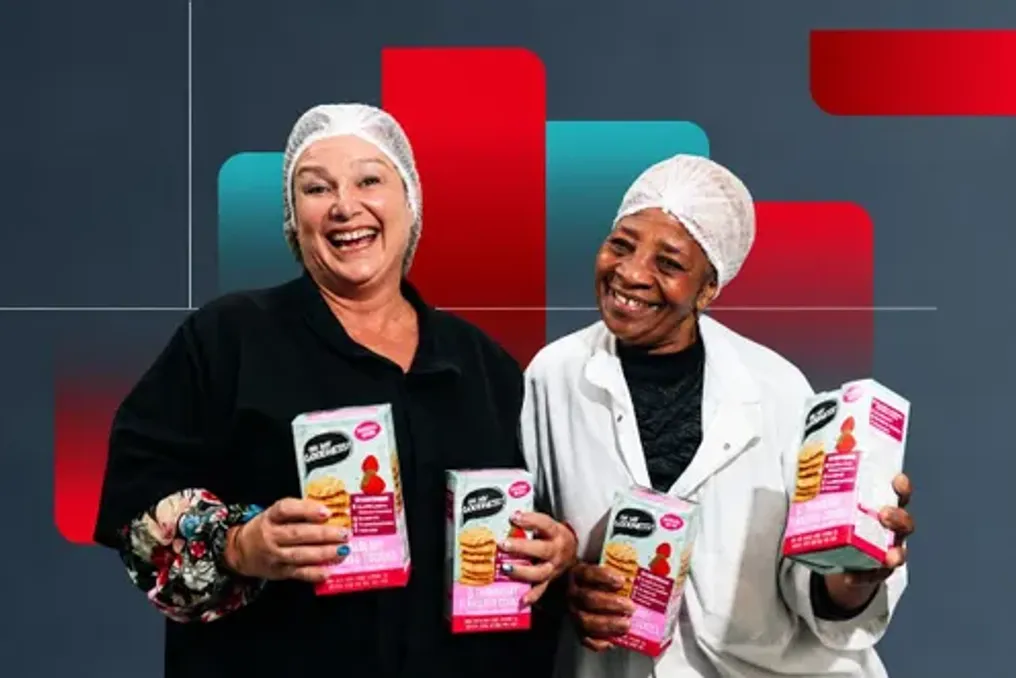
South African Small and Medium Enterprises Survive, But Face Scaling Challenges
Read more
IOL
iol.co.za

South African Small and Medium Enterprises Survive, But Face Scaling Challenges

Small, medium, and micro-enterprises (SMEs) in South Africa have long been considered the backbone of the economy, but the latest report, 'State of SMEs in South Africa 2026,' reveals a worrying reality. While survival rates are increasing, the task of scaling up remains difficult.

According to the report published by Shoprite Group, financing continues to be an almost insurmountable barrier. Although 'financial support' is a constant theme across all regions, sizes, and demographic groups, the vast majority of businesses rely on self-funding.

Over 90% of SMEs use their own resources and personal connections, with bank loans accounting for only 9.7%, and grants and investors making up about 2–3%. More than half of respondents (57.4%) did not even seek funding, making capital for growth inaccessible to most.

Nicolene Gericke from Antjie’s Handmade Naturals emphasizes that the problem is not just access, but also alignment with needs: 'SMEs are looking for financing that will help them manage growth opportunities and cash flow pressure, not just long-term debt.'

There is a clear mismatch between available financial products and the day-to-day realities of trading companies. Many acknowledge the importance of financing, but it remains relatively inaccessible or underutilized.

This grim picture is linked to a more serious structural problem within the sector: longevity does not equate to growth. Approximately one-third of South African SMEs have been operating for over 20 years, but most employ fewer than five people.

The report notes that 'overcoming difficulties is an achievement; turning this resilience into a larger, job-generating business is a separate task that the small business ecosystem has been slowly addressing.' The data shows a paradox: SMEs are becoming more resilient, ambitious, and competitive, yet remain at a size that limits their broader economic impact.

Lungi Ndelu and Gugu Dlamini from Bethel Estate warn that the South African SME ecosystem has reached a critical transition point. The challenge is no longer just helping businesses survive tough conditions, but supporting sustainable enterprises in transitioning to scale.

Gender disparity exacerbates this issue. Although women own a significant 37% of surveyed businesses and start new ventures, fewer of them scale their operations. Growth is still largely controlled by men.

The report found that 'women remain strongly represented in small businesses, indicating that the problem lies in securing the capital and support needed for growth.' It added that 'the gap widens with business size, suggesting not so much entry barriers as growth barriers,' highlighting systemic inequality in access to capital and supply chains.

Geography adds another layer of complexity. The SME landscape is uneven: urban businesses 'primarily struggle with financing and procurement access,' while 'small urban businesses face difficulties with supplier availability and customer reach,' and rural firms 'are trying to solve logistical problems before any other issues become relevant.'

The report recommends avoiding a one-size-fits-all solution, insisting that 'bridging geographical inequality requires a targeted, localized approach, not a single national model.'

Despite the challenges, positive aspects in the sector cannot be ignored. There is a 'hard-earned confidence' in the face of two decades marked by 'power outages, Rand volatility, Covid-19, and municipal dysfunction.' More businesses than before 'describe themselves as expanding,' with profitability and competitiveness rising, and an impressive 85% of owners expecting 'moderate or high growth next year.'

Business maturity is also improving. 'More than half (53.6%) of businesses report a net profit after tax above 10%, while fewer report merely breaking even. Growth forecasts remain strong,' the report states. SMEs are 'strengthening internal discipline and responding more effectively to market pressures,' demonstrating 'higher operational efficiency, greater profitability, and growing confidence in their ability to compete.'

The corporate sector in South Africa is becoming more active. Shoprite Group's commitment serves as an example: in 2026, they procured 'over R18.5 billion worth of products from small suppliers owned by black women, and R1.7 billion worth of fresh produce from South African SMEs.' Their strategy, aimed at 'increasing spending on SMEs, especially those owned by black and black women,' seeks to help move 'beyond mere survival and achieve sustainable growth' through market access, capacity building, and sustainability initiatives.

Arthur Goldstuck, CEO of World Wide Worx, succinctly summarizes the core issue: 'South African SMEs can overcome difficulties and survive, but growth is an entirely different challenge. The main problem for SMEs is how to scale.'

Ultimately, the 2026 report sounds like a call: helping South African SMEs survive was a necessary battle, but the war to transform resilience into scale is just beginning. Without targeted, stage-specific interventions, the promise of SMEs remains painfully unfulfilled.
Similar stories

South African economy shows mixed indicators despite some improvements
Read more
iol.co.za

South African economy shows mixed indicators despite some improvements

Although economic indicators point to the resilience of the South African economy, the observed improvements have not yet translated into the desired boost in growth and job creation.

Data on South Africa's second-quarter economic growth is expected to be released on Tuesday. This data will provide a fresh look at an economy grappling with high unemployment, weak business confidence, and the fallout from sharp fuel price hikes.

For a deeper analysis, IOL has developed its own Economic Health Index, which considers ten key metrics to form an overall score out of ten. Growth and employment carry the greatest weight in this index. This index is based on IOL's proprietary research and publicly available data, without the involvement of economists.

According to this index, positive aspects such as a healthy trade balance, a stable rand, and improved power supply are being offset by sluggish growth, exceptionally high unemployment, and reduced business activity.

Growth: The Main Indicator

Based on this index, the Gross Domestic Product (GDP), weighted at 20%, received a rating of 4 out of 10, according to first-quarter data. As a measure of the volume of goods and services produced, GDP increased by 0.5% compared to the previous three months, marking the sixth consecutive quarterly expansion.

Nevertheless, GDP is only one indicator of the economy's health, and the overall picture is far more complex. Investec economist Lara Hodges predicts that the second quarter's economy remained stagnant, with the possibility of a moderate decline. Hodges noted that the war in the Middle East, which began in late February, led to significantly increased costs due to a substantial rise in global oil prices, heavily impacting activity.

Hodges also anticipated further contractions in the manufacturing and mining sectors: manufacturing production fell by 1.6% in July, and mining fell by 4%, with both sectors having failed to contribute to economic growth for a long time. Mineral production decreased by 2.7% compared to the previous quarter in the second quarter, manufacturing contracted by 1.5% for the fourth consecutive quarter, and electricity generation dropped by 2.5%.

The labor market is one of the most obvious signs of weakness. The official unemployment rate in South Africa rose to 33.6% in the second quarter from 32.7% in the first, reaching its highest level in four years. More detailed information can be obtained from data on whether South Africans are finding jobs, whether businesses are investing, whether households are spending, or whether the country is receiving enough foreign income. Currently, these indicators tell completely different stories, according to IOL's internal economic index.

Consumers: Spending, but Cautiously

In parallel, consumers continue to spend money: real retail sales adjusted for inflation grew by 1.6% year-on-year in June and by 1.7% in the second quarter compared to the previous year. Although employed South Africans are spending, they are becoming more cautious about how they do so. According to recent NielsenIQ data, consumers are increasingly purchasing fast-moving consumer goods based on the availability of discounts.

South Africans spent R347.7 billion on FMCG goods in the first half of 2026, with sales volume increasing by 5.5% and units sold by 7.7% compared to the same period last year. Zak Khairi, CEO of NIQ South Africa, noted: 'The theme of the first half of the year was the consumer, who continued to become more cautious and price-sensitive.'

Meanwhile, the FNB/BER consumer confidence index paints a significantly weaker picture. The index sharply dropped from minus seven in the first quarter to deeply negative minus 19 in the second quarter because the rise in fuel prices hit household budgets. As Investec chief economist Annabel Bishop previously noted: 'Changes in inflation affect consumer purchases because real incomes determine the ability to spend on goods and/or take on debt.'

She added that 'the distorting effects of inflation give a false impression of consumer purchasing power based on their disposable income.'

Inflation: Some Relief, New Risk

There has been some easing since then. Consumer price inflation slowed more than expected, standing at 4.3% in July compared to 5% in June, and food and non-alcoholic beverage inflation is now below 1%, the lowest figure in 16 years. However, the recent increase in petrol prices by R1.34 per liter and wholesale diesel by as much as R3.15 per liter will negatively impact the cost of living—which, according to DebtBusters' fifth annual money stress tracker, is the main problem keeping South Africans awake.

Before the price hike, Bishop warned that rising prices in the region would push inflation up. She stated: 'Although CPI is expected to peak, a further sustained escalation of the Middle East war could disprove this.'

Tensions in the region have intensified in recent days. The conflict between the US and Iran escalated after the expiration of the 60-day talks on the Strait of Hormuz, accompanied by intense air skirmishes and rising regional tension.

Trade and Rand: Bright Spots

Despite this, South Africa recorded a trade surplus of R20.1 billion in July, and its current account was already in surplus in the first quarter—indicating that exports are a positive factor for the health of the South African economy. The rand has also proven surprisingly resilient. Bianca Bothes, CEO of Citadel Global, reported that the currency traded around R15.98 per dollar last week, strengthening by approximately 2% compared to the previous month.

Bothes emphasized: 'Overall, the rand is in a good position at the current level, but it remains a volatile reflection of global risk appetite.'

Peter Little, fund manager at Anchor Capital, noted that the rand rose by 2.6% in August, becoming the second best-performing major currency for the month, while the JSE's ALSI rose by 4.6%.

Business Confidence: Still Reserved

Businesses are facing difficulties: the RMB/BER business confidence index fell to 38 in the third quarter from 39, significantly below the neutral level of 50, indicating that nearly two-thirds of respondents remain dissatisfied with the current business climate. Bishop noted that business confidence has been suppressed since the global financial crisis, exacerbated by years of state capture and low growth, averaging around 38 since mid-2008, excluding the COVID-19 lockdown period. Confidence improved from late 2024 to early 2026 due to improved political sentiment and investor mood, lower inflation, and reduced power outages, but higher fuel costs have once again damaged profitability. Bishop reported that Investec has revised its 2026 GDP growth forecast from 1.5% to 1.3%.

Industrial Overview: Mixed

At the manufacturing level, the Absa Purchasing Managers' Index (PMI) fell from 46.8 in July to 45.8 in August, marking the fourth consecutive decline and the weakest figure of the year. Despite this, the Absa indicator reflecting expected business conditions in six months jumped by 5.4 points to 54.7, returning to the expansionary zone. The broader private sector PMI from S&P Global also remained above the 50-point dividing line between contraction and expansion, reaching 50.5 in August compared to 50.3 in July.

Electricity is another area where conditions have substantially improved, though structural limitations in South Africa remain. Eskom reported that in its latest financial year, there were only four days of power outages compared to 329 days two years ago, although municipal debt and grid issues remain serious concerns. Thus, while the figures suggest the South African economy is holding up, the improvements have not yet translated into the most important aspects: stronger growth and more jobs.

Problems of South African State-Owned Enterprises: Why Failures Are Rewarded
Read more
iol.co.za

Problems of South African State-Owned Enterprises: Why Failures Are Rewarded

A serious question arises not whether state-owned enterprises can be saved, but who will finally have the courage to confront those who are the creators of repeated failures. It is worrying to watch politicians approve annual reports while the author remains in the dark, observing through a smartphone.

South Africans are accustomed to two versions of reality. One is presented in glossy annual reports, filled with photos of smiling executives, colorful charts, and carefully chosen terms like sustainability, stakeholder value, and transformation. The other reality manifests when a pensioner waits three weeks to restore electricity; when passengers stand for hours due to locomotive stoppages; when municipalities cannot provide water, and ports idle while neighboring economies develop.

One reality is printed, and the other is lived. The troubling question is not why state-owned enterprises fail, but why so many people continue to benefit from these failures. State-owned enterprises were not originally conceived as investment tools for political networks; they were built as economic engines. For example, Eskom was created to electrify the country, Transnet to advance the economy, Denel to strengthen strategic capabilities, PRASA to transport ordinary workers, and the South African Post Office to connect communities. SAA was supposed to represent the country abroad. Each existed with one purpose—to serve society. Today, many of them seem to be trapped in another mission—protecting those who manage the decline.

The figures paint a painful picture. Eskom's debt exceeds 400 billion rand, and billions of funds have been transferred from taxpayers to keep power stations running. Transnet's operational failures have cost the South African economy hundreds of billions due to export delays, port congestion, and paralyzed freight transport. The South African Post Office had to declare business rescue after years of growing losses, resulting in thousands of job losses. South African Airways could only survive after repeated government bailout packages worth tens of billions of rand, transforming into a much smaller airline.

Every bailout package begins with the same promise: 'This time it will be different.' The taxpayer has become South Africa's most loyal shareholder—the only shareholder who never receives dividends, demanding only more capital. Meanwhile, another scenario quietly repeats itself: productivity falls, auditors express concerns, Parliament asks tough questions, and the media reports on a new scandal.

However, executive compensation often remains strikingly stable. Bonuses, retention incentives, and generous gifts appear. There is a suspicion that failure has become the safest career path in South African public administration. Imagine a private business that rewards executives after losing customers, market share, and billions in revenue. Investors would revolt, boards of directors would resign, and CEOs would be replaced. But in some parts of the public sector, explanations often replace accountability. Failure becomes a communication exercise, not a consequence of leadership.

What is even more alarming is what happens inside these organizations. Every structure eventually produces people who ask uncomfortable questions: accountants, compliance officers, internal auditors, and ordinary employees who still believe that politicians mean what they say. Many discover something that simply doesn't add up: a dubious contract, a rushed procurement process lacking results. They watch a consultant earn millions while projects collapse. They speak up. Usually, that is when their problems begin.

South Africa has witnessed repeated accusations in both government departments and state-owned enterprises, where whistleblowers describe intimidation, disciplinary action, and career destruction. Not every accusation proves true, and many require proper investigation. This is the essence—an independent investigation, not an internal inquiry. Too often, investigations seem less interested in finding facts than in determining who disrupted organizational harmony. The question subtly shifts: not what happened, but who revealed it. The whistleblower slowly becomes the problem, and the accused becomes the victim.

The institution speaks of culture, trust, alignment, and professional conduct. Soon the conversation stops being about corruption; it moves to behavioral issues and workplace relationships. The sickness hides for a while, remaining just a harbinger. Corporate language has perfected the art of masking institutional decay. Words become an anesthetic: transformation, strategic repositioning, business optimization, and so on.

You can read some annual reports and conclude that these organizations are thriving. Then comes load shedding. Ports stop. Railways cease movement. Water supply systems collapse. The South African population has learned an unpleasant lesson: annual reports increasingly describe intentions, while citizens experience results that do not always align.

There is another rarely discussed silence: how much public money has been spent defending labor disputes that should never have existed? Millions of rands have been spent across South Africa on litigation, disciplinary hearings, settlements, and recovery after recognizing unfair dismissal. Some employees eventually return to work, others receive compensation, and some never recover professionally, despite winning. The taxpayer finances both sides: lawyers, investigations, settlements. Then the organization publishes another commitment to ethical leadership. No annual report truly reflects the human cost: broken marriages, depression hidden behind professional smiles, children watching their parent leave home every morning without a job. A reputation that never fully recovers. Wrongful dismissals rarely make headlines, but they consume enormous public resources. Responsible managers often continue to operate seamlessly.

Perhaps the biggest irony is that South Africa is not lacking in politicians. Legislation regulating public finance, procurement, labor relations, and corporate governance is one of the most comprehensive in the world. The problem has never been the absence of rules; it has been the selective application of consequences. Delayed accountability becomes denied accountability. Oversight without enforcement turns into a public performance. Management without courage becomes ornamentation.

This is not an attack on all civil servants. Thousands come to work daily trying to keep life going in dying systems, despite budget cuts, political interference, and unattainable expectations. Many managers serve sincerely and honestly. Many board members ask difficult questions. Many auditors do excellent work, and they deserve recognition. But honesty, locked in a compromised system, cannot save institutions forever. Ultimately, systems crush individuals.

Citizens also bear responsibility. We have become experts at creating outrage. Every scandal dominates the headlines. Every commission produces huge volumes of documents. Every report causes temporary anger, and then a new scandal emerges. The previous one quietly disappears. Institutional memory becomes astonishingly short. Public fatigue becomes the greatest ally of institutional failure. Perhaps the most dangerous phrase in South African governance is not corruption, but 'business as usual.' These three words have normalized decay.

We no longer ask why trains break down; we ask when. We no longer ask why the power goes out; we ask how long. We no longer ask why a manager stays after repeated failures; we ask who will replace him. Expectations have fallen along with productivity. Perhaps this is the greatest victory—not financial theft, but psychological theft, the theft of national expectations.

True reform will require what annual reports cannot create: consequences. Boards of directors must be accountable for measurable results. Executive compensation must reflect public effectiveness, not contractual rights. Independent investigations must defend the truth, not careers. Whistleblowers must become national assets, not organizational enemies. Parliamentary oversight must go beyond televised hearings and move into coercive action. Above all, South Africa needs a cultural shift where leadership once again carries risk. Leadership without consequences is management; leadership with accountability is public service.

Until then, this pattern will repeat: another glossy report, another strategic vision, another recovery plan, another bailout package, another bonus, another whistleblower, another investigation, another apology. The country deserves better than meticulously managed decline. State-owned enterprises were never intended to be havens where failure is rewarded and honesty is professionally dangerous. They were built to carry the nation's hopes. The question is no longer whether they can be restored. The question is who will finally have the courage to hold the architects of repeated failures accountable. Because when collapse becomes profitable, hyenas no longer wait outside the gates—they have already taken seats on the board of directors.

Popular