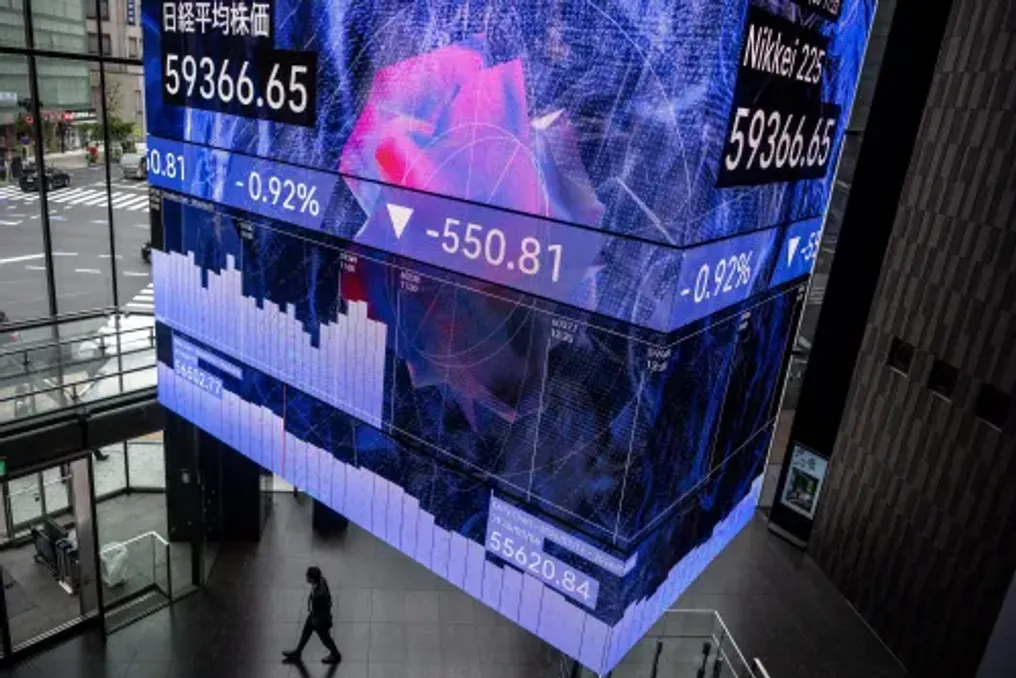
Following declines on Wall Street and in Europe, Asian stock markets fluctuated between gains and losses on Wednesday morning. Investors remained cautious ahead of the Federal Reserve's announcement regarding a potential interest rate hike later in the day.
Brent crude oil maintained a high level, reaching $107.85 per barrel on Tuesday morning, although it fell by 0.83% overnight. The military conflict in the Middle East and associated supply risks continued to pressure prices.
The Rand currency remained stable, strengthening slightly against the US dollar to R16.24, despite overall market caution before the Fed meeting and the attractiveness of US Treasury yields approaching 5%.
According to an Investec report, since inflation significantly exceeds the US central bank's target and oil prices remain above $100, markets estimate the probability of a 25 basis point rate hike at nearly 90%. This would be the first increase since 2023. This situation has seriously undermined the rally in global stocks, which reached record highs in the first half of the year, and there is growing speculation that officials may announce another hike by the end of the year.
The South African Reserve Bank's Monetary Policy Committee is expected to announce a 25 basis point rate hike at its next meeting on September 23.
One-off hike or more?
Last month, Fed Chair Kevin Warsh strengthened rate hike forecasts during a speech that was deemed hawkish at the central bankers and economists meeting in Jackson Hole, Wyoming. Expectations that inflation will remain high for an extended period contributed to the 10-year US Treasury yield rising above five percent this week—a level not seen since 2007 before the global financial crisis.
Matt Waller from FOREX.com noted that 'for traders, the most interesting part of the statement will be the vote, specifically how many of the 12 members (if any) will vote to keep interest rates unchanged.' He added that 'if there are three or more dissenting votes, or if Chairman Warsh himself votes against it (which is unlikely), even an immediate rate hike could be viewed as a potential one-off 'insurance hike,' rather than necessarily the start of a new hiking cycle.' Conversely, a unanimous decision to raise rates makes another hike this year more likely.
Asian stocks show slowdown
After declines on Wall Street and in Europe, Asian stocks showed alternating gains and losses on Wednesday morning. Tech companies were also trying to process the call from artificial intelligence leaders to slow down development in this sector, according to AFP.
Declines were recorded in Tokyo, Shanghai, Sydney, and Manila, while Hong Kong, Singapore, Wellington, Taipei, and Jakarta also showed decreases. Seoul remained unchanged.
David Chow from Invesco stated that 'currency markets still expect the consensus that US inflation will eventually return to two percent.' However, he also noted that 'it is very likely that US inflation will stabilize closer to three percent.' In this environment, where the central bank is perceived as less reliable in curbing inflation, investors may become less inclined to hold US dollars, simply because US interest rates are higher.
The Bank of England is expected to maintain its base rate on Thursday, as the UK economy struggles with growth. Attention is also drawn to the planned meeting between US President Donald Trump and his Chinese counterpart Xi Jinping; reports suggest they may agree to reduce some tariffs. Bloomberg reported that both sides are considering reducing tariffs on certain goods, including American energy and agricultural products, which could extend the one-year truce agreed in 2025 following Trump's global tariff campaign.
Key figures around 4:30 AM (SA time)
Data on commodity prices and stock indices were presented, including the fall in WTI and Brent, the rise of the Hong Kong index, the decline of the Shanghai composite index, as well as changes in currency pairs such as dollar/yen and euro/dollar.